

Category: Financing
A Smart Way to Lower Your Mortgage Payment (Without Refinancing)
Over the past few years, many homeowners in Arlington and Alexandria secured historically low interest rates. If that sounds like you, refinancing in today’s higher-rate environment probably isn’t very appealing. But there’s another strategy that often flies under the radar: mortgage recasting. What Is a Mortgage Recast? A mortgage recast allows you to make a large lump-sum payment toward your loan’s principal, and then have your lender re-amortize the remaining balance. In simple terms, that means: Your monthly payment decreases Your interest rate stays the same Your loan term stays the same You avoid a full refinance and most closing...
What Mortgage Underwriters Actually Care About
When most buyers think about qualifying for a mortgage, one number tends to steal the spotlight: the credit score. And while it absolutely plays a role, it’s only one piece of a much bigger puzzle. Mortgage underwriters look at your entire financial picture to determine risk and long-term affordability. Their goal isn’t just to approve a loan—it’s to make sure the loan makes sense for both you and the lender. Here’s what underwriters actually care about when reviewing your file. Income Stability (Not Just Income Amount) Underwriters aren’t only interested in how much you earn. They want to understand how...
2026 Mortgage Rate Outlook: What Buyers Should Expect
Mortgage rates have been a major topic over the past few years. From 2023 through 2025, buyers dealt with higher rates than many expected. As we look ahead, one big question remains: what will mortgage rates look like in 2026? While no forecast is guaranteed, most experts agree on one thing. Rates are expected to be more stable in 2026. Some modest improvement is possible, but dramatic drops are unlikely. The General Mortgage Rate Outlook for 2026 Most industry forecasts point to mortgage rates leveling off or easing slightly next year. Compared to recent highs, this would be a welcome...
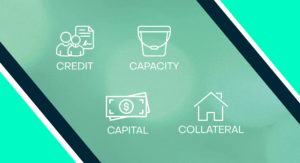
Understanding the 4 Cs of Mortgage Lending
When you apply for a mortgage, lenders take a close look at your overall financial picture to determine whether you qualify and how much risk you present as a borrower. To do this, they rely on what’s known as the 4 Cs of mortgage lending: Credit, Capacity, Capital, and Collateral. Together, these factors help lenders assess your financial stability, your ability to comfortably handle a mortgage payment, and the strength of the property backing the loan. Here’s a clear, easy-to-understand breakdown of each component and why it matters. 1. Credit Your credit history paints a picture of how you’ve managed...
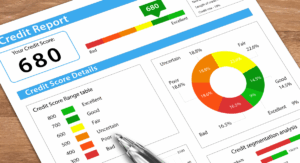
FICO vs. Credit Karma: Why Your Scores Differ
If you’ve checked your credit score on Credit Karma and then applied for a mortgage, you’ve probably noticed the numbers don’t quite match. That’s because lenders and consumer sites use different credit scoring models. What Is a FICO Score? FICO (Fair Isaac Corporation) created the most widely used credit scoring model in the U.S. Your FICO score—ranging from 300 to 850—represents your credit risk and helps lenders decide: Whether to approve your loan What interest rate to offer How much credit to extend It’s based on five factors: Payment history (35%) – Whether you pay on time Amounts owed (30%)...
Understanding PMI and How to Remove It
Private Mortgage Insurance, or PMI, is a common part of many home loans, especially for buyers who put down less than 20% on a conventional mortgage. While it may feel like just another added expense, understanding PMI can help you plan ahead and know when you’ll be able to remove it. What is PMI? PMI is insurance that protects the lender in case a borrower defaults on their loan. It does not benefit the homeowner directly, but it does make it possible for buyers to purchase a home with a smaller down payment. How Much Does PMI Cost? The cost...